Relationship Banker, Consumer Sylvie Dufresne
Relationship Banker, Consumer
[email protected] | (401) 555-0129 | Providence, United States
Profile
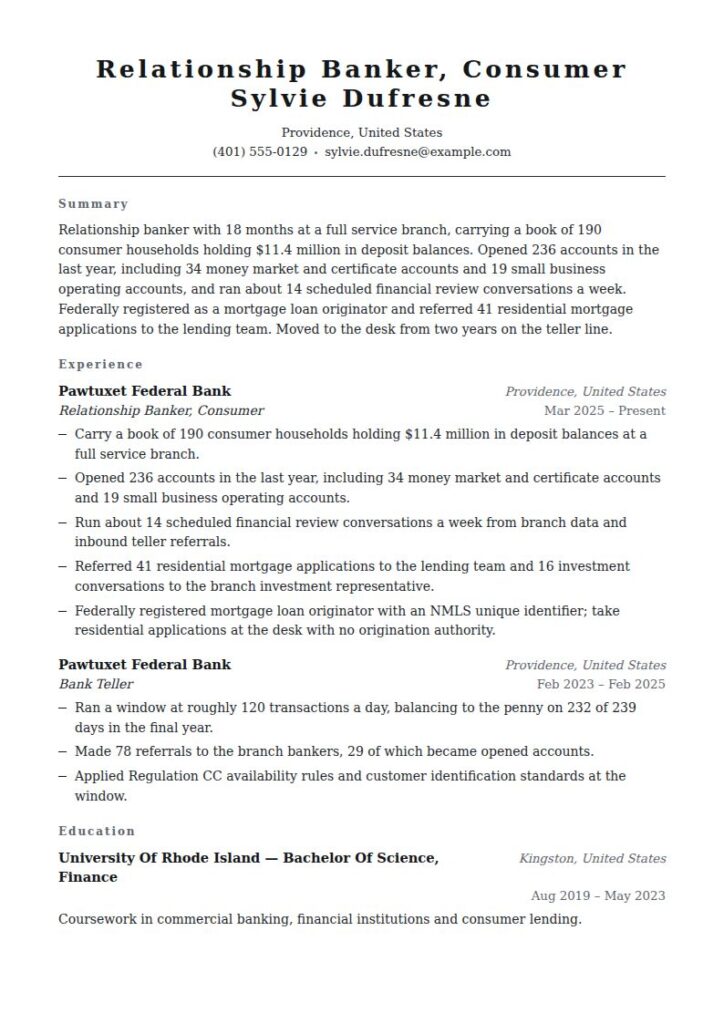
Relationship banker with 18 months at a full service branch, carrying a book of 190 consumer households holding $11.4 million in deposit balances. Opened 236 accounts in the last year, including 34 money market and certificate accounts and 19 small business operating accounts, and ran about 14 scheduled financial review conversations a week. Federally registered as a mortgage loan originator and referred 41 residential mortgage applications to the lending team. Moved to the desk from two years on the teller line.
Work Experience
03/2025 - Present, Relationship Banker, Consumer, Pawtuxet Federal Bank, Providence, United States
- Carry a book of 190 consumer households holding $11.4 million in deposit balances at a full service branch.
- Opened 236 accounts in the last year, including 34 money market and certificate accounts and 19 small business operating accounts.
- Run about 14 scheduled financial review conversations a week from branch data and inbound teller referrals.
- Referred 41 residential mortgage applications to the lending team and 16 investment conversations to the branch investment representative.
- Federally registered mortgage loan originator with an NMLS unique identifier; take residential applications at the desk with no origination authority.
02/2023 - 02/2025, Bank Teller, Pawtuxet Federal Bank, Providence, United States
- Ran a window at roughly 120 transactions a day, balancing to the penny on 232 of 239 days in the final year.
- Made 78 referrals to the branch bankers, 29 of which became opened accounts.
- Applied Regulation CC availability rules and customer identification standards at the window.
Education
08/2019 - 05/2023, Bachelor of Science, Finance, University of Rhode Island, Kingston, United States
Coursework in commercial banking, financial institutions and consumer lending.
Skills
Financial review and discovery conversations, 70
Consumer deposit account opening, 85
Money market and certificate products, 70
Customer identification program, 80
Regulation CC availability, 80
Core banking platform and digital account opening, 75
Customer relationship management and pipeline tracking, 70
Languages
English, native
French, intermediate
Certificates
04/2025, Federally registered mortgage loan originator, Nationwide Multistate Licensing System, under Regulation G, 12 CFR 1007
Registration current. Unique identifier provided to consumers on request and in initial written communication, and not published.
03/2026, Bank Secrecy Act and anti-money laundering training, Pawtuxet Federal Bank, annual program under 31 CFR 1020.210
Summary
A banker resume is a one to two page document built on the book: how many relationships and how much in deposit balances you carry, which products you can open yourself, which registrations you hold, and where your referrals go once a conversation moves past your authority. This guide gives you three adaptable versions and current Bureau of Labor Statistics pay for the occupations that cover this work.
Banker resume examples by experience level
A banker resume is a one to two page document built on the book: how many relationships you carry, how much sits in them, which products you opened, which registrations you hold, and where a conversation goes once it passes your authority.
The first problem is the word itself. "Banker" is used loosely across the industry, and the same title covers a person opening checking accounts at a branch counter and a person managing a portfolio of small business relationships worth tens of millions in deposits. A hiring manager reading your resume cannot tell which one you are from the title, and will not guess in your favor. Your resume has to say it.
Resume guide for a banker resume
This guide and the corresponding banker resume example will cover:
- How to write a banker resume, section by section
- Why the title tells a reader nothing, and what to write instead
- Three adaptable summaries: new banker, personal banker and senior relationship banker
- What NMLS registration means for a banker resume, and when it is required
- What the market pays, bracketed across the occupations that actually cover this work
How to write a banker resume
Six blocks: contact header, summary, the book block, experience, skills and systems, education and registrations. One page for your first three or four years, two once the book is large enough that the numbers need room.
The book block goes directly under the summary, for the same reason a sales resume leads with quota and attainment. Everything else you could write is describable by anyone who has sat at a branch desk. Balances, relationships, products placed and referrals converted cannot be.
| Section | What it is answering | Where it goes |
|---|---|---|
| The book block | Which kind of banker is this, and how big is what they carry? | Directly under the summary |
| Experience | What did they grow, place and refer, in numbers? | Reverse chronological, numbers in every bullet |
| Registrations | Can they take a mortgage application? Can they sell an investment? | Its own line, not buried in skills |
| Skills and systems | Which core platform and CRM do they already know? | Short grouped block |
Write balances and relationships, not activity
Most banker resumes are written in activity: meetings held, calls made, products discussed, appointments booked. Activity is what your manager tracked on a Monday. It is not what a hiring manager is buying.
What they are buying is a book. Write it as one: how many relationships or households, what those relationships hold in deposit balances, what the average relationship is worth, and how much of that you grew rather than inherited.
"Carry a book of 480 households holding $62 million in deposit balances, up $8.4 million net new in the last 12 months" tells a reader your segment, your scale and your trajectory in one sentence. Nothing about calls per week does that.
Run the finished file through the free ATS checker before you send it. Bank recruiting systems parse structured fields out of your file before a human opens it, and a two column layout is where that goes wrong.
Choosing the best resume format for a banker resume
Reverse chronological, one to two pages. Banking hiring runs on verification: dates, titles, registrations and a background and credit check that has to line up with what you wrote. A format that softens the timeline creates doubt in a compliance review that you will never be present for.
Two pages is justified once your book carries real balances and a referral pipeline with funded volume behind it. Below that, one page is stronger: a thin book stretched over two pages reads exactly like a thin book stretched over two pages.
Include your contact information
| ✅ Right | ❌ Wrong |
|---|---|
| Sylvie Dufresne | Sylvie Dufresne |
| Personal Banker, Consumer and Small Business, NMLS registered | Banking professional and financial services expert |
| Book: 480 households, $62M in deposit balances | Top performer |
| (401) 555-0129, [email protected], Providence, RI | (401) 555-0129, [email protected] |
The second line is doing the work the title should do and does not. Segment, scope and registration status in eight words tells the reader which of the four jobs called "banker" you actually hold.
Make use of a summary
Four lines: what kind of banker, how big the book, one growth number, and what you refer rather than close.
Relationship banker with 18 months at a full service branch, carrying a book of 190 consumer households holding $11.4 million in deposit balances. Opened 236 accounts in the last year, including 34 money market and certificate accounts and 19 small business operating accounts, and ran about 14 scheduled financial review conversations a week. Federally registered as a mortgage loan originator and referred 41 residential mortgage applications to the lending team. Moved to the desk from two years on the teller line.
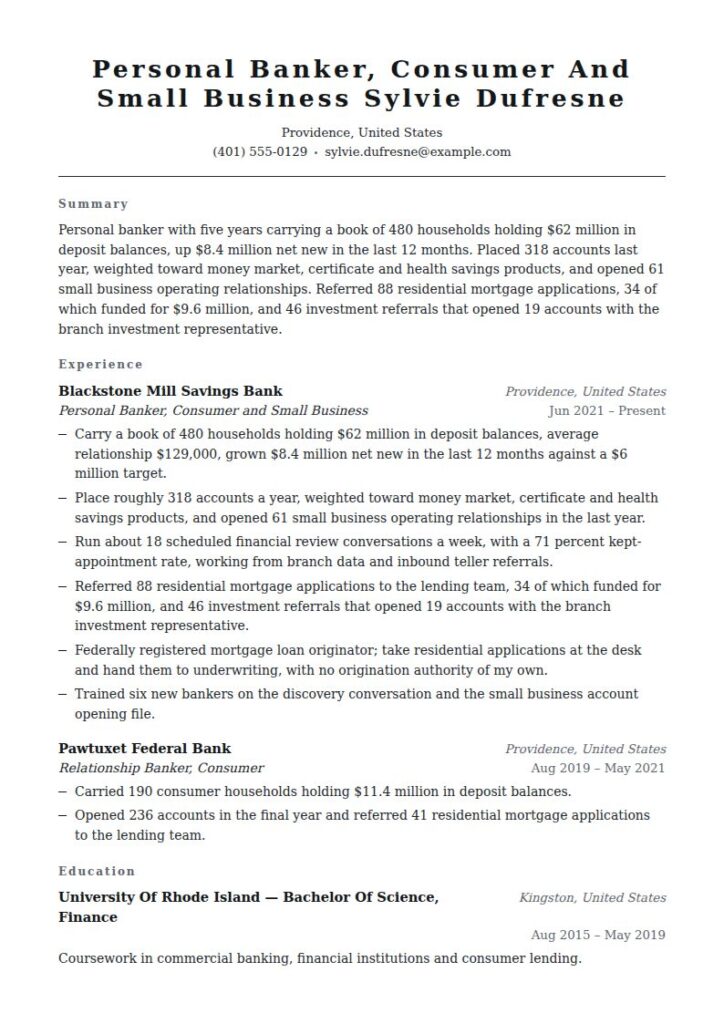
Personal banker with five years carrying a book of 480 households holding $62 million in deposit balances, up $8.4 million net new in the last 12 months. Placed 318 accounts last year, weighted toward money market, certificate and health savings products, and opened 61 small business operating relationships. Referred 88 residential mortgage applications, 34 of which funded for $9.6 million, and 46 investment referrals that opened 19 accounts with the branch investment representative.
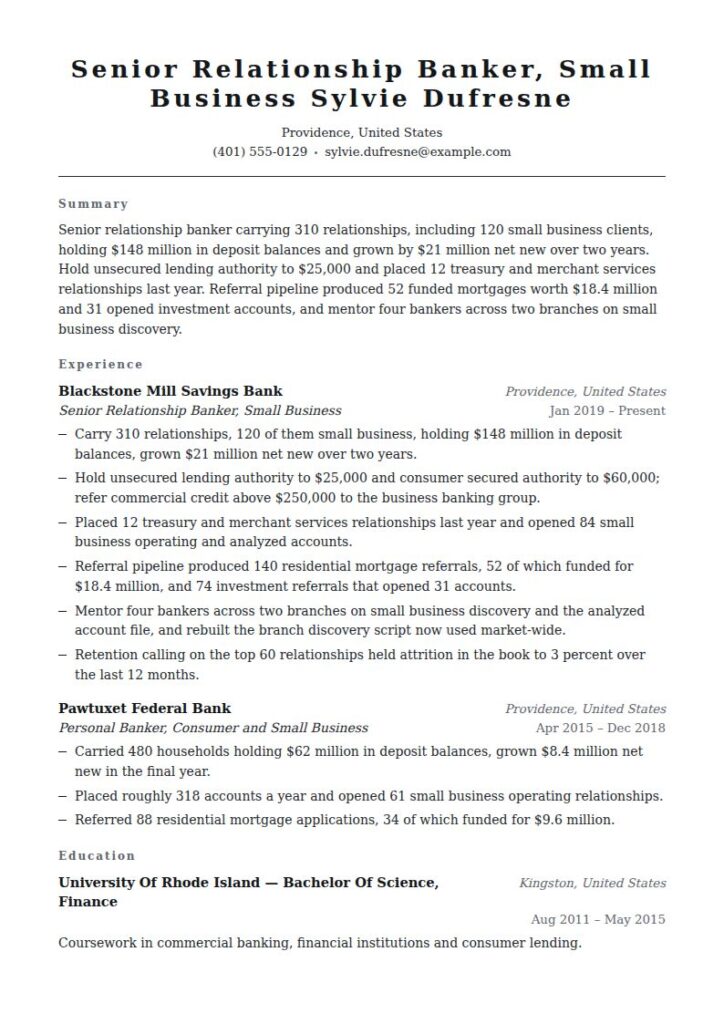
Senior relationship banker carrying 310 relationships, including 120 small business clients, holding $148 million in deposit balances and grown by $21 million net new over two years. Hold unsecured lending authority to $25,000 and placed 12 treasury and merchant services relationships last year. Referral pipeline produced 52 funded mortgages worth $18.4 million and 31 opened investment accounts, and mentor four bankers across two branches on small business discovery.
Right vs wrong: the same banker summary, twice
| ✅ Right | ❌ Wrong |
|---|---|
| Carry a book of 480 households holding $62 million in deposit balances. | Experienced banker with a strong portfolio of loyal clients. |
| Up $8.4 million net new in the last 12 months. | Consistently exceeded sales goals and growth targets. |
| 88 mortgage referrals, 34 funded for $9.6 million. | Skilled at cross-selling and building lasting relationships. |
The right column is a book. The left column is a personality. Banks hire books.
Outline your experience
Bank, branch or market, city, dates, and then three to five bullets. Every bullet carries a number: balances, relationships, accounts, referrals, funded volume or people developed.
| Instead of | Use |
|---|---|
| Managed a portfolio of banking clients | Carried 480 households holding $62 million in deposit balances, average relationship $129,000 |
| Consistently met and exceeded sales targets | Grew the book $8.4 million net new in 12 months against a $6 million target |
| Cross-sold a range of banking products | Placed 318 accounts, weighted to money market, certificates and health savings, plus 61 small business operating relationships |
| Referred clients to mortgage and investment partners | 88 mortgage referrals, 34 funded for $9.6 million; 46 investment referrals, 19 accounts opened |
| Provided excellent customer service | Ran about 18 scheduled financial review conversations a week, with a 71 percent kept-appointment rate |
Personal Banker, Consumer and Small Business, Blackstone Mill Savings Bank, Providence, RI, June 2021 to Present
Carry a book of 480 households holding $62 million in deposit balances, average relationship $129,000, grown $8.4 million net new in the last 12 months against a $6 million target.
Place roughly 318 accounts a year, weighted toward money market, certificate and health savings products, and opened 61 small business operating relationships in the last year.
Run about 18 scheduled financial review conversations a week, with a 71 percent kept-appointment rate, working from branch data and inbound teller referrals.
Referred 88 residential mortgage applications to the lending team, 34 of which funded for $9.6 million, and 46 investment referrals that opened 19 accounts with the branch investment representative.
Federally registered mortgage loan originator; take residential applications at the desk and hand them to underwriting, with no origination authority of my own.
Say which banker you are: the book, the products and the authority
This is the block that separates a banker resume from every other banker resume, and it exists because the job title does not do its job.
The same word covers a person opening consumer checking accounts at a branch desk, a personal banker carrying a mass-affluent book, a small business banker working a market by industry, a private banker with a high net worth portfolio, and in commercial banking a relationship manager underwriting credit. These are different jobs with different hiring bars. A reader who cannot tell which one you are defaults to the smallest.
Segment and book: 480 consumer and small business households, $62 million in deposit balances, average relationship $129,000, Providence metro
Products I open myself: checking, savings, money market, certificates, health savings accounts, small business operating and analyzed accounts, unsecured personal loans to $25,000, credit cards, merchant services
What I refer out: residential mortgage to the lending team, investments and annuities to the branch investment representative, commercial credit above $250,000 to the business banking group
Registrations and authority: federally registered mortgage loan originator with an NMLS unique identifier; no securities registrations; fee waiver authority to $150 per relationship per quarter
Four lines, four questions. What do you carry, what can you actually sell, what leaves your desk, and what can you sign. Answer those and the title stops mattering.
If you take mortgage applications at a bank, you are federally registered
Under the SAFE Act, an employee of a bank, savings association or credit union who acts as a residential mortgage loan originator must register with the Nationwide Multistate Licensing System and obtain a unique identifier, rather than hold the state license that non-depository originators need (Regulation G, 12 CFR 1007, Consumer Financial Protection Bureau).
There is a narrow exception. Section 1007.101(c)(2)(i) covers an employee who acted as a mortgage loan originator for five or fewer residential mortgage loans in the preceding 12 months. Many branch bankers sit just under that line, which is exactly why the status is worth stating.
The registrant also has to give the unique identifier to consumers on request, before acting as an originator, and in the initial written communication with a consumer (12 CFR 1007.105(b)). If you are registered, put "NMLS registered" and the status on the resume; do not publish the identifier itself on a public job board. If you are not registered, say what you refer instead, because a reader who cannot tell will assume the more limited answer.
Build a snapshot of your key skills
Ten to fourteen entries in three groups: the consultative work, the product set, and the systems. Name the core banking platform and the customer relationship system, because a bank that runs the same stack reads that as weeks of onboarding saved.
Client work: Financial review and discovery conversations, Needs-based product matching, Small business cash flow discovery, Relationship retention and attrition calls, Complaint resolution and fee exception handling
Products: Consumer deposit accounts, Money market and certificates, Health savings accounts, Small business operating and analyzed accounts, Unsecured personal lending, Credit cards, Merchant services, Treasury basics
Compliance and systems: Customer identification program, Bank Secrecy Act and anti-money laundering, Regulation CC availability, Core banking platform, Customer relationship management and pipeline tracking, Digital account opening
Keep it honest. If you ran the discovery conversation for treasury management and then handed it to a treasury officer, write "referred", not "placed". Bank interviews probe the product line by line, and a correction in the room costs more than the smaller claim on the page.
List your education and registrations
A bachelor's degree is typical for the business and financial occupations that cover this work, according to the Bureau of Labor Statistics Occupational Outlook Handbook, though a great many bankers came up through the branch without one. Put the registrations where they will be seen, because they are a gate rather than an ornament.
Bachelor of Science, Finance, University of Rhode Island, Kingston, RI, 2019
Federally registered mortgage loan originator, Nationwide Multistate Licensing System, registered 2021, current
No securities registrations held; investment conversations referred to the branch investment representative
Bank Secrecy Act and anti-money laundering training, completed annually, most recently 2026
Certificate in Business and Commercial Lending, American Bankers Association, 2024
Stating what you do not hold is unusual and it works. A hiring manager reading a banker resume is working out what you can and cannot legally do, and answering before you are asked reads as someone who understands the boundary rather than someone who has never met it.
Choose the right layout and design
Single column, 11 or 12 point, clear headings, no photograph, no charts, no skill bars. Save as PDF unless the portal says otherwise, named for yourself and the role: sylvie-dufresne-personal-banker-resume.pdf.
State your segment in the header line, because the title does not. Give the book as relationships and balances, with the growth number separated from the inherited number. Name the products you can open yourself and the ones you refer. State your NMLS registration status and any securities registrations, or say plainly that you hold none. Put funded volume behind mortgage referrals where you have it.
Do not write "portfolio of clients" without a number attached. Do not present a book you inherited as a book you built. Do not list a product you have referred as one you have placed. Do not put a customer name, an account number or a balance anywhere in the file, and never bring a client list to an interview. Do not publish your NMLS unique identifier on a public job board.
Banker job market and outlook
There is no Occupational Outlook Handbook profile for "banker". The Handbook covers broad occupations rather than job titles, and the work a branch or relationship banker does is split across three published occupations rather than gathered into one.
The honest way to read the market is to bracket the role between those three: securities, commodities and financial services sales agents, which is where branch and financial services sales work sits; loan officers, where the lending side of the job sits; and personal financial advisors, where a banker who takes securities registrations tends to go next.
| Bracketing occupation | Employment, 2025 | Projected change, 2025 to 2035 | Annual openings | Median annual wage, May 2025 |
|---|---|---|---|---|
| Securities, commodities and financial services sales agents | 531,000 | 1 percent growth, +7,500 | About 35,100 | $78,660 |
| Loan officers | 283,000 | 1 percent growth, +3,100 | About 17,100 | $76,690 |
| Personal financial advisors | 299,400 | 1 percent growth, +4,100 | About 17,100 | $105,070 |
Source: U.S. Bureau of Labor Statistics, Occupational Outlook Handbook, May 2025 wage data and 2025 to 2035 projections.
The same job pays differently depending on where it sits
Within securities, commodities and financial services sales agents, 54 percent of employment sits in credit intermediation and related activities, which is banking, and 33 percent in securities and financial investments. The median wage in credit intermediation was $61,720 in May 2025, against $103,030 in securities and financial investments (BLS Occupational Outlook Handbook, May 2025).
The same split runs through the other two brackets. Loan officers had a median of $76,690 overall and $76,070 in credit intermediation, where 80 percent of them work. Personal financial advisors had a median of $105,070 overall, $96,010 in credit intermediation and $120,870 in securities and financial investments, where 65 percent of them work (BLS Occupational Outlook Handbook, May 2025).
Read together, those numbers describe the actual career ladder inside a bank. The branch desk is the least paid position from which the same conversation can be had. What raises the number is the registration that lets you keep the business instead of referring it out, and the segment you move into once you have it. That is why the registration line and the referral pipeline belong on your resume: they are the two things a hiring manager uses to place you on that ladder.
What salary you can expect as a banker
There is no published median for the job title "banker", and quoting one would mean inventing it. What can be said accurately is where the three occupations that cover this work sit, which is what a compensation team is working from anyway.
Securities, commodities and financial services sales agents had a median annual wage of $78,660 in May 2025, with the lowest 10 percent under $48,040 and the highest 10 percent over $212,880. Loan officers had a median of $76,690, from under $39,430 to over $153,180. Personal financial advisors had a median of $105,070, from under $50,190 to over $357,020 (BLS Occupational Outlook Handbook, May 2025).
Three things move you inside that spread. Industry first: within financial services sales agents, banking paid a median of $61,720 against $103,030 in securities and investments (BLS, May 2025). Registration second, because it decides whether a conversation ends at your desk or leaves it. Segment third, since a small business or private client book with a lending component is priced differently from a consumer deposit book of the same headcount. Name all three on the page.
Key takeaways for a banker resume
- Say which kind of banker you are in the header line; the title will not do it for you.
- Give the book as relationships and balances, and separate what you grew from what you inherited.
- List the products you open yourself and the ones you refer, as two different lines.
- State your NMLS registration status plainly, and say if you hold no securities registrations.
- Put funded volume behind referrals wherever you have it, not just referral counts.
- Name the core platform and the customer relationship system you already know.
- Keep customer names, account numbers and balances out of the file entirely.
Build your banker resume in 15 minutes with our AI resume builder.
Related accounting and finance resume examples
- Personal banker resume
- Bank teller resume
- Bank manager resume
- Loan officer resume
- Loan processor resume
- Credit analyst resume
- Financial advisor resume
- Investment banker resume
- Compliance officer resume
- Finance manager resume
- Financial analyst resume
- Accountant resume
Pair it with a matching banker cover letter.
Banker resume questions, answered
What does "banker" actually mean on a job posting?
It depends entirely on the bank, which is the problem. The same word covers a branch desk opening consumer accounts, a personal banker with a mass-affluent book, a small business banker working a market, a private banker with a high net worth portfolio, and in commercial banking a relationship manager who underwrites credit. Read the posting for the segment, for whether NMLS registration is required, and for a named lending authority or portfolio size. Those three identify the job far better than the title does.
How long should a banker resume be?
One page for your first three or four years. Two once the book carries real balances and you have a referral pipeline with funded volume behind it. Not three, and not two pages of activity metrics dressed as results.
Can I put my production numbers on a resume?
Your own aggregate production is normally fine: balances under management, accounts opened, net new growth, referral counts and funded volume. What is not fine is anything that identifies a customer, so no names, account numbers, balances of individual relationships, or documents exported from a bank system. If your employment agreement restricts disclosure of internal sales data, describe scale in ranges and percentages instead of exact figures, and never take a client list with you.
Do I need to be NMLS registered to work as a banker?
Only if you act as a residential mortgage loan originator. Under the SAFE Act, employees of banks, savings associations and credit unions who originate residential mortgages must register with the Nationwide Multistate Licensing System and obtain a unique identifier rather than hold a state license (Regulation G, 12 CFR 1007, Consumer Financial Protection Bureau). There is an exception at 12 CFR 1007.101(c)(2)(i) for an employee who originated five or fewer residential mortgage loans in the preceding 12 months. Many branch bankers sit under that threshold and refer instead, which is a perfectly good answer as long as your resume says so.
Do I need a Series 6 or Series 7 to be a banker?
Not for a deposit and consumer lending role. Securities registration is what lets you sell investment products, and FINRA is the main licensing organization for the securities industry, with employers usually sponsoring registration after hire (BLS Occupational Outlook Handbook). Plenty of bankers work an entire career unregistered and refer investment conversations to a licensed representative. Taking registrations is one of the clearest routes up the pay range: personal financial advisors had a median annual wage of $105,070 in May 2025 against $78,660 for financial services sales agents (BLS, May 2025).
What do I write if my bank does not use the word "book"?
Build one from what your bank does track: households or relationships assigned to you, deposit balances in them, net new growth over a stated period, accounts opened by product family, and referrals sent with how many converted. Every bank measures those under some name. The word is not what matters; the shape of the number is.