Assistant Branch Manager Leonora Vasilenko
Assistant Branch Manager
[email protected] | (303) 555-0188 | Aurora, United States
Profile
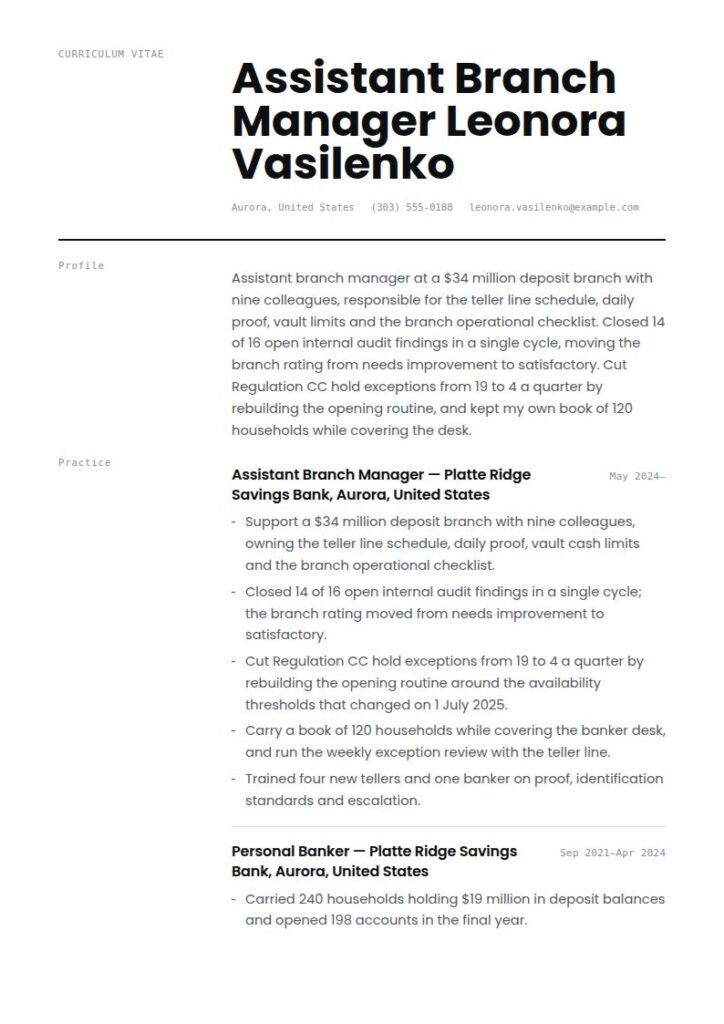
Assistant branch manager at a $34 million deposit branch with nine colleagues, responsible for the teller line schedule, daily proof, vault limits and the branch operational checklist. Closed 14 of 16 open internal audit findings in a single cycle, moving the branch rating from needs improvement to satisfactory. Cut Regulation CC hold exceptions from 19 to 4 a quarter by rebuilding the opening routine, and kept my own book of 120 households while covering the desk.
Work Experience
05/2024 - Present, Assistant Branch Manager, Platte Ridge Savings Bank, Aurora, United States
- Support a $34 million deposit branch with nine colleagues, owning the teller line schedule, daily proof, vault cash limits and the branch operational checklist.
- Closed 14 of 16 open internal audit findings in a single cycle; the branch rating moved from needs improvement to satisfactory.
- Cut Regulation CC hold exceptions from 19 to 4 a quarter by rebuilding the opening routine around the availability thresholds that changed on 1 July 2025.
- Carry a book of 120 households while covering the banker desk, and run the weekly exception review with the teller line.
- Trained four new tellers and one banker on proof, identification standards and escalation.
09/2021 - 04/2024, Personal Banker, Platte Ridge Savings Bank, Aurora, United States
- Carried 240 households holding $19 million in deposit balances and opened 198 accounts in the final year.
- Referred 52 residential mortgage applications to the lending team and placed 22 small business operating accounts.
Education
08/2017 - 05/2021, Bachelor of Science, Business Administration, Metropolitan State University of Denver, Denver, United States
Coursework in financial institutions, management and business statistics.
Skills
Teller line scheduling and daily proof, 85
Internal audit remediation, 80
Regulation CC funds availability, 85
Vault cash limits and dual control, 85
Bank Secrecy Act and anti-money laundering at branch level, 75
Coaching and new hire onboarding, 75
Core banking platform and branch reporting, 80
Languages
English, native
Ukrainian, native
Certificates
01/2022, Federally registered mortgage loan originator, Nationwide Multistate Licensing System, under Regulation G, 12 CFR 1007
Registration current; identifier provided to consumers rather than published.
01/2026, Bank Secrecy Act and anti-money laundering training, Platte Ridge Savings Bank, annual program under 31 CFR 1020.210
Summary
A bank manager resume is a two page document that treats the branch as two things at once: a balance sheet with deposits, loan production and fee income on it, and a compliance surface that gets audited and examined. This guide gives you three adaptable versions, a branch scorecard block, the rules on what you may disclose about an examination, and current Bureau of Labor Statistics pay.
Bank Manager resume examples by experience level
A bank manager resume is a two page document that treats the branch as two things at once. It is a balance sheet, carrying deposits, loan production and fee income against a cost base that is mostly people. It is also a compliance surface, tested by internal audit, sampled in examinations and answerable for every cash count, hold and report the branch produces.
Most bank manager resumes describe only the first, and describe it vaguely: grew deposits, led a high performing team, delivered excellent customer service. The second is where a regional manager's real anxiety sits, because a branch that grows and fails an audit is a worse problem than a branch that does neither.
Resume guide for a bank manager resume
This guide and the corresponding bank manager resume example will cover:
- How to write a bank manager resume, section by section
- Why the branch scorecard carries both the numbers and the controls
- Three adaptable summaries: assistant manager, branch manager and multi-branch manager
- What you may and may not say about an audit or an examination
- What the market pays, and why the published figure needs reading carefully
How to write a bank manager resume
Six blocks: contact header, summary, the branch scorecard, experience, leadership and compliance skills, education and registrations. Two pages is normal, because the balance sheet and the control record both need room and neither compresses well.
The branch scorecard sits directly under the summary. A regional manager scanning applications is trying to size you in ten seconds: how big a branch, how many people, growing or shrinking, clean or not. Four lines answer all four.
| Section | What it is answering | Where it goes |
|---|---|---|
| Branch scorecard | How big, how many people, growing, and clean? | Directly under the summary |
| Experience | What did the branch do under you, in numbers, over what period? | Reverse chronological, two roles deep |
| Controls and audit | Findings, repeat findings, exception rates, exam support | Inside each role, not as a separate claim |
| Education and registrations | Degree, SAFE Act status, compliance training currency | Last block, brief |
Write the audit you inherited, not only the one you finished with
A clean audit history is worth less on a resume than a fixed one, because a clean history could mean a branch nobody stressed.
Write the whole arc: what the rating was when you arrived, how many findings there were, how many were repeats, and what the next cycle produced. "Inherited an unsatisfactory internal audit with nine repeat findings; closed all nine and the following two cycles came back satisfactory with no repeats" is the most valuable sentence a branch manager can put on a page.
Then say what you changed, not just what the number did. A rewritten opening and closing routine, a dual control schedule that actually gets followed, a weekly exception review with the line. Regional managers hire the method, because the method is what transfers to their problem branch.
Run the finished file through the free ATS checker before you apply. Bank recruiting platforms read the file into structured fields before a human sees it, and a dense two page manager resume in columns is exactly what breaks.
Choosing the best resume format for a bank manager resume
Reverse chronological, two pages. Every bank hire ends in a background and credit check and a verification of dates and titles, and a format that blurs the timeline creates work for a recruiter and questions for a compliance reviewer.
Go two roles deep and no further. A branch manager with twelve years does not need the teller line written out; one line acknowledging the operational grounding is enough, and it is worth having, because a manager who has balanced a drawer is trusted differently on a cash finding.
Include your contact information
| ✅ Right | ❌ Wrong |
|---|---|
| Leonora Vasilenko | Leonora Vasilenko |
| Branch Manager, $126M deposits, 11 FTE, Aurora CO | Results-driven banking leader and team builder |
| SAFE Act registered; internal audit satisfactory, no repeat findings | Excellent leadership and compliance skills |
| (303) 555-0188, [email protected], Aurora, CO | (303) 555-0188, [email protected] |
Three facts in the header line size you before the reader reaches the summary: deposit base, headcount and market. A regional manager with a $90 million branch and a $400 million branch to fill knows immediately which conversation this is.
Make use of a summary
Four lines: branch size and headcount, the growth number with a period attached, the control record, and one thing you fixed.
Assistant branch manager at a $34 million deposit branch with nine colleagues, responsible for the teller line schedule, daily proof, vault limits and the branch operational checklist. Closed 14 of 16 open internal audit findings in a single cycle, moving the branch rating from needs improvement to satisfactory. Cut Regulation CC hold exceptions from 19 to 4 a quarter by rebuilding the opening routine, and kept my own book of 120 households while covering the desk.
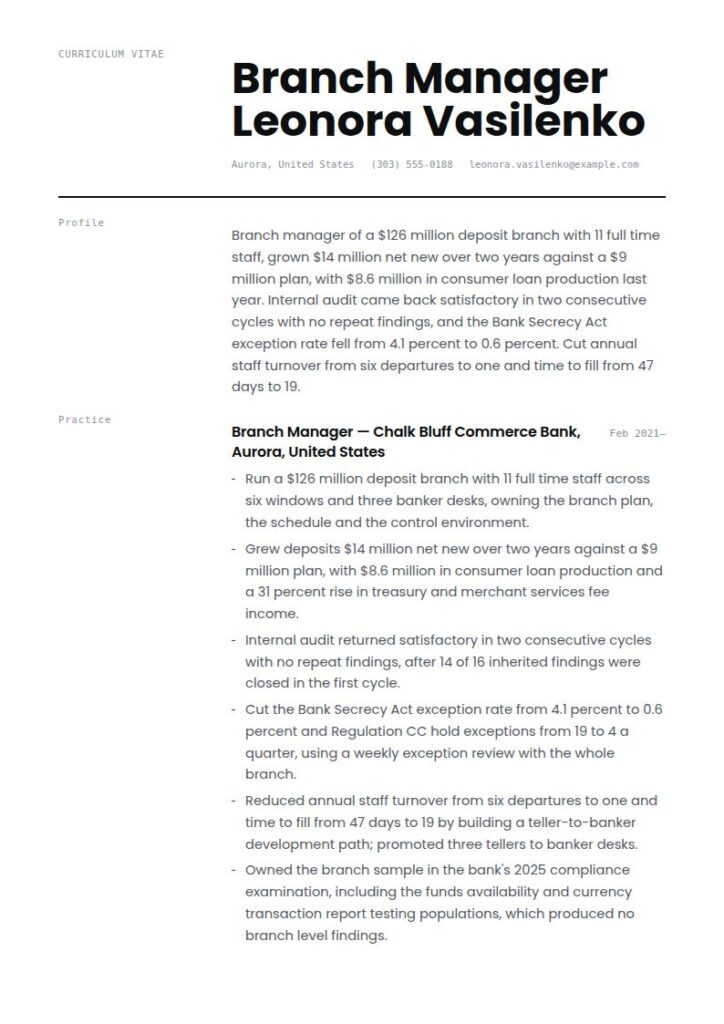
Branch manager of a $126 million deposit branch with 11 full time staff, grown $14 million net new over two years against a $9 million plan, with $8.6 million in consumer loan production last year. Internal audit came back satisfactory in two consecutive cycles with no repeat findings, and the Bank Secrecy Act exception rate fell from 4.1 percent to 0.6 percent. Cut annual staff turnover from six departures to one and time to fill from 47 days to 19.
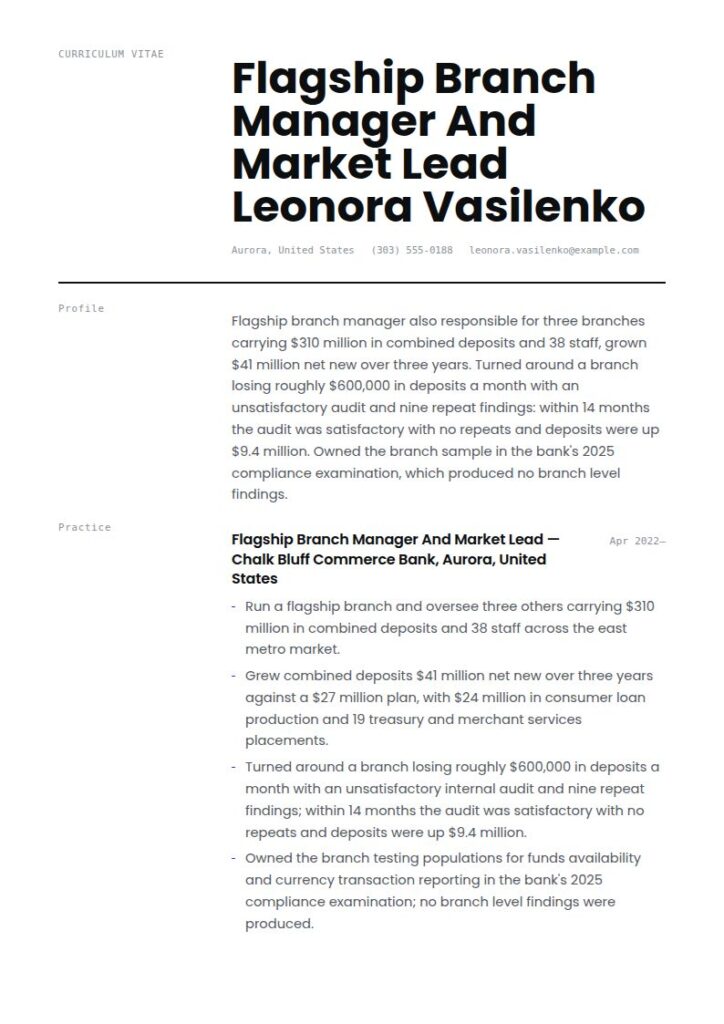
Flagship branch manager also responsible for three branches carrying $310 million in combined deposits and 38 staff, grown $41 million net new over three years. Turned around a branch losing roughly $600,000 in deposits a month with an unsatisfactory audit and nine repeat findings: within 14 months the audit was satisfactory with no repeats and deposits were up $9.4 million. Owned the branch sample in the bank's 2025 compliance examination, which produced no branch level findings.
Right vs wrong: the same bank manager summary, twice
| ✅ Right | ❌ Wrong |
|---|---|
| Branch manager of a $126 million deposit branch with 11 full time staff. | Experienced branch leader managing a high performing team. |
| Grew $14 million net new over two years against a $9 million plan. | Consistently exceeded deposit growth and sales targets. |
| Two consecutive satisfactory internal audits with no repeat findings. | Ensured full compliance with all banking regulations and procedures. |
The right column can be compared with the branch a regional manager is trying to fill. The left column can be written by anyone who has ever seen a branch.
Outline your experience
Bank, branch or market, city, dates, then four to six bullets for the current role and two or three for the one before. Deposits, growth, production, headcount, turnover, findings and exceptions, each with a number and a period.
| Instead of | Use |
|---|---|
| Managed all aspects of branch operations | Ran a $126 million deposit branch with 11 full time staff across six windows and three banker desks |
| Grew deposits and exceeded targets | Grew deposits $14 million net new over two years against a $9 million plan, with $8.6 million in consumer loan production |
| Ensured compliance with banking regulations | Two consecutive satisfactory internal audits with no repeat findings; Bank Secrecy Act exception rate down from 4.1 percent to 0.6 percent |
| Led and developed a high performing team | Cut turnover from six departures a year to one and time to fill from 47 days to 19; promoted three tellers to banker |
| Turned around an underperforming branch | Took a branch losing about $600,000 in deposits a month to $9.4 million of growth in 14 months, with the audit moving from unsatisfactory to satisfactory |
Branch Manager, Chalk Bluff Commerce Bank, Aurora, CO, February 2021 to Present
Run a $126 million deposit branch with 11 full time staff across six windows and three banker desks, owning the branch plan, the schedule and the control environment.
Grew deposits $14 million net new over two years against a $9 million plan, with $8.6 million in consumer loan production and a 31 percent rise in treasury and merchant services fee income.
Internal audit returned satisfactory in two consecutive cycles with no repeat findings, after 14 of 16 inherited findings were closed in the first cycle.
Cut the Bank Secrecy Act exception rate from 4.1 percent to 0.6 percent and Regulation CC hold exceptions from 19 to 4 a quarter, using a weekly exception review with the whole branch.
Reduced annual staff turnover from six departures to one and time to fill from 47 days to 19 by building a teller-to-banker development path; promoted three tellers to banker desks.
Owned the branch sample in the bank's 2025 compliance examination, including the funds availability and currency transaction report testing populations, which produced no branch level findings.
The branch scorecard: balances, audit results and what the exam found
This is the block that does not appear on other branch manager resumes, and it is the one a regional manager actually reads.
A branch is judged on two axes that are usually written about separately and should not be. Growth without a control record is a risk the reader has to price; a control record without growth is a branch being managed rather than run. Put both on the page, in four lines, with the same rigor.
Balance sheet: $126 million in deposits, $14 million net new over two years against a $9 million plan, $8.6 million consumer loan production last year, fee income up 31 percent
People: 11 full time staff across six windows and three banker desks; turnover down from six departures a year to one; time to fill 19 days; three internal promotions to banker
Controls: two consecutive satisfactory internal audits with no repeat findings; 14 of 16 inherited findings closed in the first cycle; Bank Secrecy Act exception rate 4.1 percent to 0.6 percent; Regulation CC hold exceptions 19 to 4 a quarter
Examination support: owned the branch sample for funds availability and currency transaction reporting in the 2025 compliance examination; no branch level findings
Four lines, four different questions. How big is it. Who runs it and do they stay. Is it clean, and was it clean when you arrived. And did it hold up when someone from outside looked.
What you may say about an examination, and what you may not
Community Reinvestment Act performance evaluations are public. The written evaluation "is public information and can be obtained through the institution or its supervisory agency", and the ratings are one of four categories: outstanding, satisfactory, needs to improve, and substantial noncompliance (FFIEC, CRA Ratings). If your bank's public CRA evaluation is relevant and you contributed to it, you may reference it.
Safety and soundness examination reports and their component ratings are a different matter. They are confidential supervisory information, they belong to the agency and the bank, and they do not go on a resume, into a cover letter, or into an interview answer. Neither do internal audit reports, exception reports or workpapers.
What you can always write is your own contribution and its outcome, described without the document: which testing populations your branch owned, what you remediated beforehand, and whether the branch produced findings. That is the substance a regional manager wants, and it is disclosable.
Build a snapshot of your key skills
Twelve to fifteen entries in three groups: running the branch, the control environment, and the people work. Name the core platform and the scheduling and reporting tools, because a bank on the same stack reads that as a shorter ramp.
Branch performance: Deposit growth planning, Consumer loan production, Fee income and treasury referral, Branch profit and loss review, Lobby traffic analysis and scheduling, Small business market calling
Control environment: Internal audit remediation, Bank Secrecy Act and anti-money laundering oversight, Customer identification and beneficial ownership, Regulation CC funds availability, Cash limits, dual control and vault custody, Fraud and elder financial exploitation escalation, Examination sample preparation
People: Hiring and onboarding, Teller to banker development paths, Coaching to a scorecard, Performance management and documentation, Scheduling to measured traffic, Succession and bench planning
List your education and registrations
A bachelor's degree is the typical entry-level education for financial managers, the occupation that covers banking management, according to the Bureau of Labor Statistics Occupational Outlook Handbook, which also notes that five years or more of related work experience is typical. Many branch managers came up through the branch instead, which is worth showing rather than hiding.
Bachelor of Science, Business Administration, Metropolitan State University of Denver, Denver, CO, 2012
Federally registered mortgage loan originator, Nationwide Multistate Licensing System, registered 2015, current
Bank Secrecy Act and anti-money laundering training, completed annually, most recently 2026, including the branch management module
Certificate in Branch Management, American Bankers Association, 2019
Progression: teller, senior teller, personal banker, assistant branch manager, branch manager
Anti-money laundering programs for banks require internal controls, independent testing, a designated compliance officer and training for appropriate personnel (31 CFR 1020.210), and a branch manager is one of the people that training is aimed at. Stating that yours is current signals that the branch will not be the reason the bank's testing comes back badly.
Choose the right layout and design
Single column, 11 or 12 point type, clear headings, no photograph and no charts. Two pages, with the scorecard high on page one where a ten second scan will find it. Save as PDF unless the portal says otherwise: leonora-vasilenko-branch-manager-resume.pdf.
Size the branch in the header line with deposits, headcount and market. Give growth as a net new figure against the plan, over a stated period. Write the audit history including what you inherited. State exception rates as before and after. Put turnover, time to fill and internal promotions on the page, because staffing is most of a branch cost base. Say which testing populations your branch owned in an examination and what came back.
Do not quote a safety and soundness examination rating, quote an examination report, or attach internal audit workpapers; those are confidential supervisory information. Do not write customer names, account numbers or balances anywhere. Do not claim a growth number without the period it covers. Do not present a branch you inherited in good shape as a turnaround. Do not describe your team in adjectives when turnover and promotions are available.
Bank manager job market and outlook
The Occupational Outlook Handbook publishes no separate profile for bank branch manager. The Handbook covers broad occupations rather than job titles, and branch management sits inside financial managers, the management occupation that covers banking and finance.
That profile needs reading carefully, because it also contains controllers, treasurers and risk managers, whose pay sits well above a branch. Treat it as the band the job sits inside, not as a branch figure. The two occupations a branch manager leads are published separately and are worth reading alongside it.
| Occupation | Employment, 2025 | Projected change, 2025 to 2035 | Annual openings | Median annual wage, May 2025 |
|---|---|---|---|---|
| Financial managers | 879,700 | 10 percent growth, +84,900 | About 65,600 | $166,570 |
| Loan officers | 283,000 | 1 percent growth, +3,100 | About 17,100 | $76,690 |
| Tellers | 339,200 | 13 percent decline, -44,700 | About 26,800 | $43,030 |
Source: U.S. Bureau of Labor Statistics, Occupational Outlook Handbook, May 2025 wage data and 2025 to 2035 projections.
Fewer windows, the same number of branches, more management
Financial managers are projected to grow 10 percent between 2025 and 2035, adding 84,900 jobs with about 65,600 openings a year, while tellers are projected to decline 13 percent over the same period (BLS Occupational Outlook Handbook, 2025 to 2035 projections). Those two lines moving in opposite directions describe the branch manager's job changing underneath them.
The branch network itself has not disappeared. The FDIC's 2025 Summary of Deposits, covering data as of 30 June 2025 and released in September 2025, reported more than 76,000 domestic offices operated by more than 4,400 FDIC-insured institutions.
What has changed is the mix inside those offices. The FDIC's 2023 National Survey of Unbanked and Underbanked Households, published 12 November 2024, found 48.3 percent of banked households naming mobile banking as their primary method of account access, with teller use as a primary method down by more than half over the preceding decade. Fewer routine transactions means smaller teller lines, more universal and banker roles, and a manager whose value sits in growth, development and controls rather than in supervising volume. Write the resume for that branch.
What salary you can expect as a bank manager
Financial managers, the occupation that covers banking management, had a median annual wage of $166,570 as of May 2025, with the lowest 10 percent under $94,310 and the highest 10 percent over $323,270. Within that occupation, 32 percent of employment sits in finance and insurance, where the median was $169,980 (BLS Occupational Outlook Handbook, May 2025).
Read that as a band rather than a branch salary. The occupation includes corporate controllers, treasurers and risk managers, and a single branch manager sits below the middle of it. The published number tells you where the career leads, not what the first branch pays.
What moves a branch manager inside the band is measurable and worth putting on the page. Deposit base comes first, because branches are graded by it and pay follows the grade. Loan and fee production comes second, since it is the part of the branch a bank can see contributing. Span comes third: a manager covering two or three branches, or carrying a small business calling responsibility, is doing a different job from a single branch manager. The control record comes fourth, because a branch with audit history behind it is the one a region has to staff with someone expensive.
Key takeaways for a bank manager resume
- Size the branch in the header line: deposits, headcount and market.
- Give growth as net new against plan, with the period it covers.
- Write the audit arc, including what you inherited, not only the clean ending.
- State exception rates as a before and an after, with the routine you changed.
- Put turnover, time to fill and internal promotions on the page.
- Describe examination support by testing population and outcome, never by quoting the report.
- Keep confidential supervisory information, customer names and balances out of the file entirely.
Build your bank manager resume in 15 minutes with our AI resume builder.
Related accounting and finance resume examples
- Bank teller resume
- Banker resume
- Personal banker resume
- Loan officer resume
- Compliance officer resume
- Finance manager resume
- Finance director resume
- Auditor resume
- Auditing clerk resume
- Credit analyst resume
- Financial analyst resume
- Accountant resume
Pair it with a matching bank manager cover letter.
Bank manager resume questions, answered
How long should a bank manager resume be?
Two pages. A branch manager has a balance sheet, a headcount, a control record and usually a turnaround worth describing, and none of that fits on one page without losing the numbers. Three pages is too many, and the way to stay at two is to go deep on the last two roles and give everything earlier a single line.
Can I put audit or examination results on my resume?
Your own branch's internal audit outcomes, described as ratings and finding counts, are normally fine and are among the strongest things you can write. What is not fine is quoting or attaching an examination report, naming a safety and soundness rating, or including internal workpapers: all confidential supervisory information. Community Reinvestment Act performance evaluations are the exception, since the written evaluation is public and the rating is one of outstanding, satisfactory, needs to improve or substantial noncompliance (FFIEC, CRA Ratings). When unsure, describe your contribution and its outcome instead of the document.
How do I write about a branch that was failing when I took it over?
Give the starting state in numbers, then the work, then the ending state with a period attached. "Inherited a branch losing about $600,000 in deposits a month with an unsatisfactory internal audit and nine repeat findings; rebuilt the opening and closing routine, ran a weekly exception review and filled two vacancies internally; within 14 months the audit was satisfactory with no repeats and deposits were up $9.4 million." Turnarounds are the most valuable thing on a branch manager resume, and they only read as turnarounds if the starting state is on the page.
Do I need to be NMLS registered as a branch manager?
Only if you personally act as a residential mortgage loan originator. The SAFE Act requires a depository institution employee who acts as a residential mortgage loan originator to register with the Nationwide Multistate Licensing System and take a unique identifier, rather than the state license a non-depository originator needs (Regulation G, 12 CFR 1007, Consumer Financial Protection Bureau). A manager who originates five or fewer residential mortgage loans in a 12 month period falls under the exception at 12 CFR 1007.101(c)(2)(i). Most branch managers register anyway, because registration is what lets them cover a banker desk on a short-staffed week, and that is worth a line on the page.
What if I am moving into branch management from retail store management?
Lead with the parts that transfer, exactly: headcount, scheduling to measured traffic, shrink or cash loss control, audit and compliance routines, hiring and turnover, and any profit and loss ownership. Then address the gap rather than hoping it goes unnoticed. Name the banking regulations you have studied, say you expect Bank Secrecy Act training in the first week, and say you understand a background and credit check is part of hiring. Banks recruit branch managers out of retail regularly; what fails is a retail resume submitted untranslated.
How do I show results if my branch is small or flat?
Use the measures a small branch still produces: net new balances rather than total, loan and fee production, referral volume converted, lobby wait times, audit findings closed, exception rates, turnover, internal promotions and training delivered. A manager of a $34 million branch who closed 14 of 16 audit findings and cut turnover to one departure a year is describing the exact method a regional manager wants for a larger branch.