Insurance Producer, Property, Casualty and Personal Lines Gerardo Kowalczyk
Insurance Producer, Personal Lines
[email protected] | (414) 555-0160 | Milwaukee, United States
Profile
Newly licensed insurance producer in Wisconsin carrying property, casualty and personal lines authority, license #WI-3308291, working a personal lines book at an independent agency. Built to 410 policies in force across 268 households and $612,000 of written premium in the first eighteen months, at 87 percent policy retention. Appointed with 4 carriers for personal auto, homeowners and umbrella, and studying for the accident and health examination to add a line by the renewal season.
Work Experience
09/2019 - Present, Insurance Producer, Personal Lines, Menomonee Valley Insurance Group, Milwaukee, United States
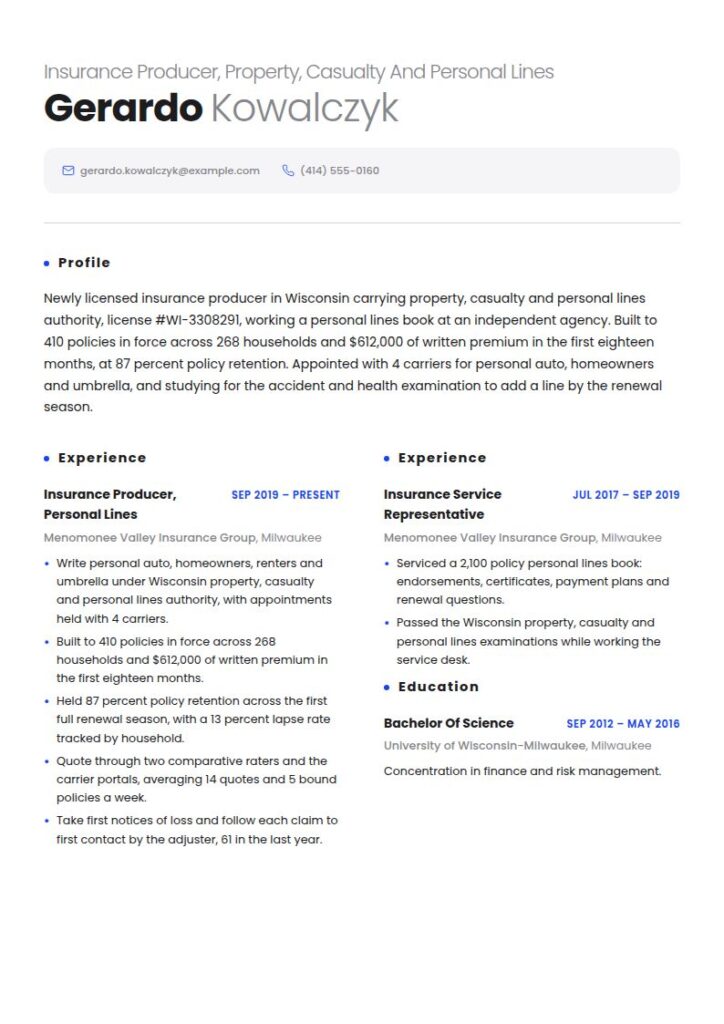
- Write personal auto, homeowners, renters and umbrella under Wisconsin property, casualty and personal lines authority, with appointments held with 4 carriers.
- Built to 410 policies in force across 268 households and $612,000 of written premium in the first eighteen months.
- Held 87 percent policy retention across the first full renewal season, with a 13 percent lapse rate tracked by household.
- Quote through two comparative raters and the carrier portals, averaging 14 quotes and 5 bound policies a week.
- Take first notices of loss and follow each claim to first contact by the adjuster, 61 in the last year.
07/2017 - 09/2019, Insurance Service Representative, Menomonee Valley Insurance Group, Milwaukee, United States
- Serviced a 2,100 policy personal lines book: endorsements, certificates, payment plans and renewal questions.
- Passed the Wisconsin property, casualty and personal lines examinations while working the service desk.
Education
09/2012 - 05/2016, Bachelor of Science, Business Administration, University of Wisconsin-Milwaukee, Milwaukee, United States
Concentration in finance and risk management.
Skills
Personal auto and homeowners underwriting appetite, 75
Comparative rating and carrier portals, 85
Renewal and remarket cycle, 70
First notice of loss handling, 80
Applied Epic and EZLynx, 85
Continuing education tracking, 80
Languages
English, native
Polish, conversational
Spanish, intermediate
Certificates
08/2019, Wisconsin Resident Insurance Producer License, Wisconsin Office of the Commissioner of Insurance, WI-3308291
Lines of authority: property, casualty and personal lines. National Producer Number 19447206. Continuing education of 24 credit hours including 3 ethics hours completed each biennial cycle.
Summary
An insurance agent resume is a one to two page document saying what you may legally sell and what you have sold: the state producer licenses you hold, the lines of authority on each, the carriers that have appointed you, and the book behind them in policies, premium and retention. This guide gives you three adaptable versions and current Bureau of Labor Statistics pay, employment and outlook data for insurance sales agents.
Insurance Agent resume examples by experience level
An insurance agent resume is a one to two page document answering two questions in order: what are you licensed and appointed to sell, and what have you actually sold.
Nothing else on the page can be read until those two are settled. An agency principal is working out whether you could write business on Monday or whether they are funding three months of licensing and carrier paperwork first, and the answer changes what you are worth.
The National Association of Insurance Commissioners describes an insurance producer as an individual who sells, solicits or negotiates insurance, and counts more than 2 million individuals and more than 236,000 business entities licensed to provide insurance services in the United States (NAIC, producer licensing topic page, checked 12 September 2026). Your resume says where in that population you sit.
Resume guide for an insurance agent resume
This guide and the corresponding insurance agent resume example will cover:
- How to write an insurance agent resume, block by block
- Producer licenses, lines of authority, appointments and why they come first
- Three adaptable summaries: newly licensed, established and senior producer
- The book: policies in force, premium, retention, lapse and cross-sold lines
- What the occupation pays and where the jobs are
How to write an insurance agent resume
Five blocks: contact header, summary, licensing and appointments, the book, then employment history, skills and education. One page while you are building a book, two once you have carried one through several renewal seasons. The licensing block goes above experience because it is a gate rather than an achievement, and because most agent resumes compress it into the single word "licensed".
| Block | What it is answering | Where it goes |
|---|---|---|
| Licenses and lines of authority | What may this person legally sell, and where? | Directly under the summary |
| Appointments | Which carriers can they place business with today? | Beside the licenses, by product type |
| The book | What have they written, and does it stay written? | Its own block, with premium and retention |
| Securities registrations | Can they touch variable products? | With the licenses, only if held |
A license is a line of authority, not a word
"Licensed insurance agent" is the least useful sentence on most agent resumes, because a producer license is not one thing. It is a state-issued license carrying named lines of authority, and each line is a separate permission.
For a resident individual producer in Wisconsin, the lines requiring an examination are life, property, casualty, personal lines, credit, title, and accident and health or sickness, while variable life and variable annuity, crop, surety, travel, attorney title and legal expense do not; a passed fingerprint check is valid for 180 days (National Insurance Producer Registry, Wisconsin resident individual licensing requirements, checked 12 September 2026).
Write yours out in full: the issuing state, the license number, the lines held and the expiry, then the non-resident states separately. A principal can verify all of it in a lookup, and the file that lets them do it in a minute moves ahead.
Put the finished file through the free Rezoom ATS resume checker first. Agencies and carriers parse applications before a human reads them, and a license table set inside a graphic is what a parser loses.
Choosing the best resume format for an insurance agent resume
Reverse chronological, with licensing directly under the summary and the book as a short table.
Continuity reads as evidence here. An agent who held the same book for five years and grew retention has demonstrated what the role exists for, because persistency is a multi-year measurement. Frequent moves are not fatal, but each needs a reason on the page, since a book does not travel with the agent.
Moving from a service role inside an agency, keep the timeline and convert what you did: policies serviced, endorsements processed, claims reported and any license gained on the way. Agencies promote from service desks routinely.
Include your contact information
| ✅ Right | ❌ Wrong |
|---|---|
| Gerardo Kowalczyk | Gerardo Kowalczyk |
| Insurance Producer, Property, Casualty, Life, Accident and Health | Licensed insurance professional |
| WI producer license #WI-3308291, NPN 19447206. Non-resident: IL, MN | Licensed and appointed in multiple states |
| (414) 555-0160, [email protected], Milwaukee, WI | (414) 555-0160, [email protected] |
Put the lines of authority in the header. A personal lines producer and one carrying life and health as well are different hires with different appointments behind them, and the header saves the reader a guess. The National Producer Number belongs there too, because it makes every other claim checkable.
Make use of a summary
Four lines: the licenses and lines, the appointments, the book in policies and premium, and one persistency or cross-sell number.
Newly licensed insurance producer in Wisconsin carrying property, casualty and personal lines authority, license #WI-3308291, working a personal lines book at an independent agency. Built to 410 policies in force across 268 households and $612,000 of written premium in the first eighteen months, at 87 percent policy retention. Appointed with 4 carriers for personal auto, homeowners and umbrella, and studying for the accident and health examination to add a line by the renewal season.
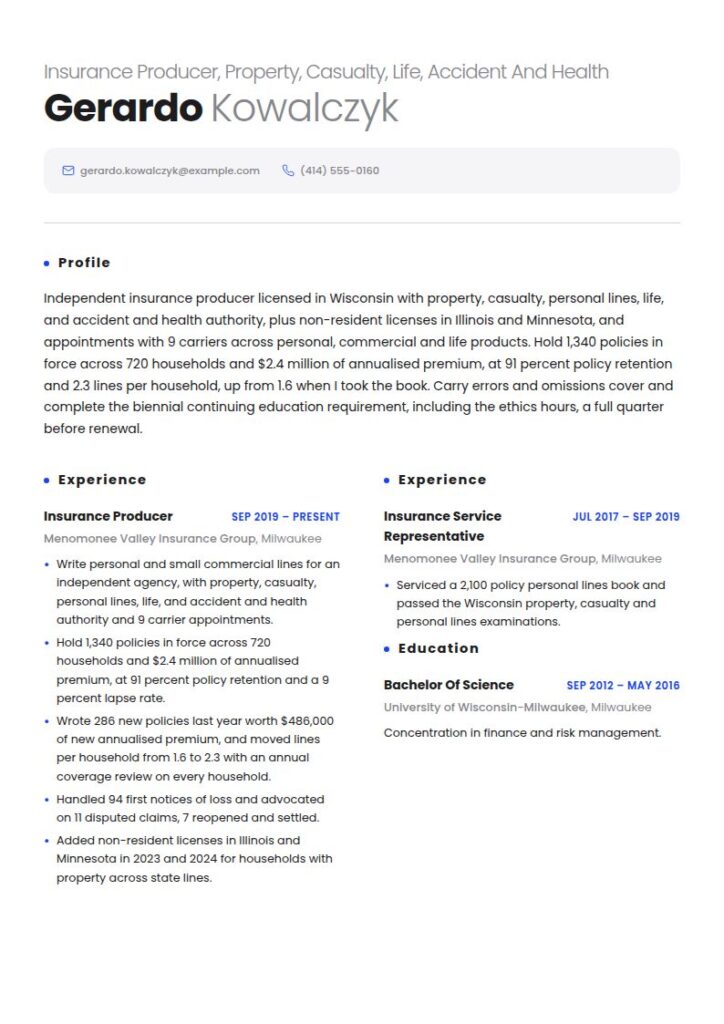
Independent insurance producer licensed in Wisconsin with property, casualty, personal lines, life, and accident and health authority, plus non-resident licenses in Illinois and Minnesota, and appointments with 9 carriers across personal, commercial and life products. Hold 1,340 policies in force across 720 households and $2.4 million of annualised premium, at 91 percent policy retention and 2.3 lines per household, up from 1.6 when I took the book. Carry errors and omissions cover and complete the biennial continuing education requirement, including the ethics hours, a full quarter before renewal.
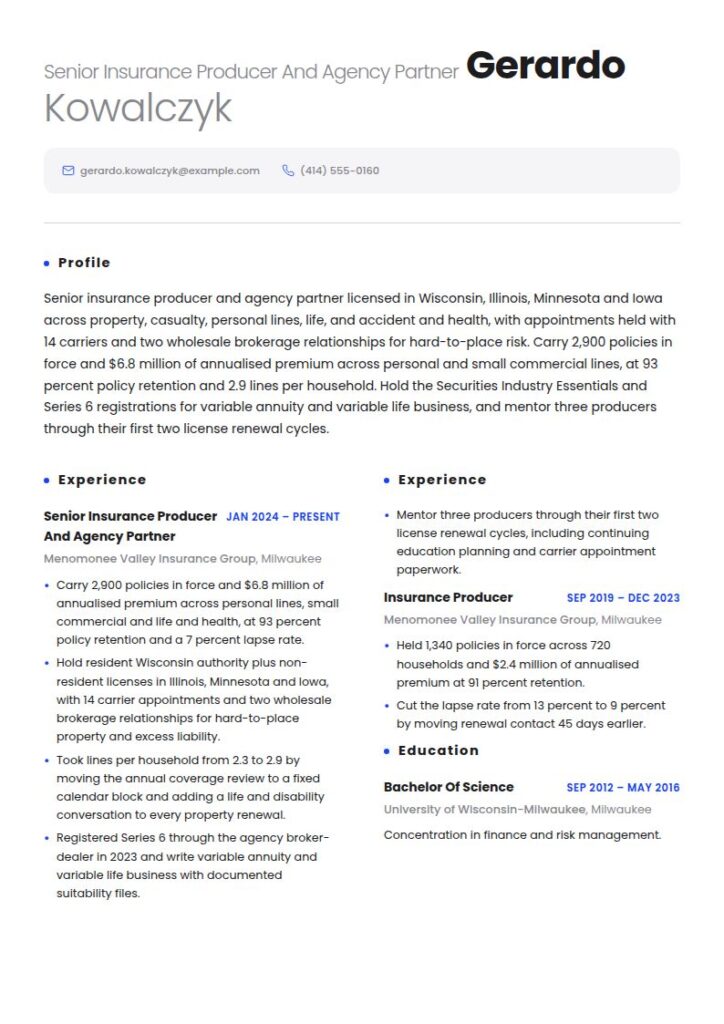
Senior insurance producer and agency partner licensed in Wisconsin, Illinois, Minnesota and Iowa across property, casualty, personal lines, life, and accident and health, with appointments held with 14 carriers and two wholesale brokerage relationships for hard-to-place risk. Carry 2,900 policies in force and $6.8 million of annualised premium across personal and small commercial lines, at 93 percent policy retention and 2.9 lines per household. Hold the Securities Industry Essentials and Series 6 registrations for variable annuity and variable life business, and mentor three producers through their first two license renewal cycles.
Right vs wrong: the same insurance agent summary, twice
| ✅ Right | ❌ Wrong |
|---|---|
| Wisconsin producer license with property, casualty, personal lines, life, and accident and health authority. | Fully licensed insurance agent with multiple certifications. |
| Appointed with 9 carriers across personal, commercial and life products. | Strong relationships with a wide range of insurance providers. |
| 1,340 policies in force across 720 households, $2.4 million of annualised premium. | Managed a substantial book of business. |
| 91 percent policy retention and 2.3 lines per household, up from 1.6. | Consistently delivered excellent client service and retention. |
The right column checks out in a state license lookup and an agency management system. The left column is what every applicant sends, and a principal learns nothing they can act on.
Outline your insurance agent experience
Agency or carrier, what it writes, who for, the book you held and the dates. Then three to five bullets, each carrying a licensing, production or persistency number.
| Instead of | Use |
|---|---|
| Sold insurance products to new and existing clients | Wrote 286 new policies last year, $486,000 of new annualised premium |
| Maintained a large book of business | Held 1,340 policies across 720 households, $2.4 million of annualised premium |
| Built strong client relationships | Took lines per household from 1.6 to 2.3 with an annual coverage review |
| Focused on client retention | Cut the lapse rate from 13 percent to 9 percent by moving renewal contact 45 days earlier |
| Assisted clients with claims | Handled 94 first notices of loss and advocated on 11 disputed claims, 7 reopened and settled |
| Worked with insurance carriers | Hold 9 carrier appointments and placed 3 hard-to-place commercial risks through wholesale brokerage |
Insurance Producer, Menomonee Valley Insurance Group, Milwaukee, WI, September 2019 to Present
Write personal and small commercial lines for an independent agency, with property, casualty, personal lines, life, and accident and health authority and 9 carrier appointments.
Hold 1,340 policies in force across 720 households and $2.4 million of annualised premium, at 91 percent policy retention and a 9 percent lapse rate.
Wrote 286 new policies last year worth $486,000 of new annualised premium, and moved lines per household from 1.6 to 2.3 with an annual coverage review on every household.
Handled 94 first notices of loss and advocated on 11 disputed claims, 7 reopened and settled.
Added non-resident licenses in Illinois and Minnesota in 2023 and 2024 for households with property across state lines.
Your lines of authority, your appointments and your book
This block is the page. Everything else is context for it.
Licenses: Wisconsin resident producer, #WI-3308291, lines of authority property, casualty, personal lines, life, and accident and health. National Producer Number 19447206. Non-resident producer licenses in Illinois (#IL-7742168) and Minnesota (#MN-2290544). All current.
Continuing education: 24 credit hours each biennial cycle including the 3 required ethics hours, banked a quarter before the renewal date.
Appointments: 9 carriers. Personal auto and homeowners with 4, umbrella with 3, small commercial and workers compensation with 2, term and permanent life with 3. Two wholesale brokerage relationships for hard-to-place property and excess liability.
Securities: Securities Industry Essentials passed 2022. Series 6 registration held through the agency's broker-dealer for variable annuity and variable life business.
Errors and omissions: agency policy, $1 million per claim and $2 million aggregate, named producer.
Book: 1,340 policies in force across 720 households. $2.4 million of annualised premium. Personal lines 71 percent, small commercial 19 percent, life and health 10 percent.
Persistency: 91 percent policy retention, 9 percent lapse rate, down from 13 percent. Lines per household 2.3, up from 1.6.
Claims advocacy: 94 first notices of loss last year, 11 disputed claims advocated, 7 reopened and settled.
Compensation model: new and renewal commission on written premium, no salary component, with a renewal trail on the in-force book.
Seven things make that block credible, and they are what an agency principal checks before the first interview.
Name the issuing authority and the lines, not the word licensed. A state department of insurance issues the license and its lines of authority decide what you may sell, so give the state, the number and every line. That difference is worth money to an agency holding appointments in one area and not another.
Add the National Producer Number. It lets a principal verify every license you claim in one lookup, and putting it on the page signals you expect to be checked.
Say where you are licensed beyond your home state, labeling resident and non-resident separately. Households with property in two states and employers with sites across a state line both require it, and an agency serving a border market treats a non-resident license as directly productive.
Put the continuing education on the page with its cycle. In Wisconsin, each resident intermediary licensed in any of the major lines must complete 24 credit hours of continuing education biennially, of which a minimum of 3 credit hours must cover ethics in insurance (Wisconsin Office of the Commissioner of Insurance, agent continuing education requirements, checked 12 September 2026). Saying you complete it early reads as operational reliability, which is what a principal is buying.
Then the part most applicants miss: appointments are not licenses, and without them you place no business. A license is permission from the state; an appointment is a carrier authorizing you to represent it. In Wisconsin an insurer initiates that appointment through a request made within 15 days of the date the agent contract is executed or the date the first insurance application is submitted, and when the relationship ends the insurer must file a termination notice within 30 calendar days (Wisconsin Administrative Code Ins 6.57, implementing s. 628.11 Wis. Stats., checked 12 September 2026). List appointments by product type and count them, because a producer arriving with appointments the agency already holds is productive immediately.
Say which model you have worked in. Captive means representing one carrier's products; independent means holding appointments with several and choosing between them; brokerage means placing risk through wholesalers. They are different jobs, and a principal hiring for one screens out the other two quickly. If you have worked in more than one, say which and when.
Finally, variable products need securities registration as well, and it is worth stating exactly. The Securities Industry Essentials examination is open to anyone aged 18 or older, does not require association with a firm, runs to 75 questions in 1 hour and 45 minutes with a passing score of 70, and its result stays valid for four years (FINRA, Securities Industry Essentials exam, checked 12 September 2026). The Series 6 sits on top: a candidate must be associated with and sponsored by a FINRA member firm, the Securities Industry Essentials is a corequisite, and it permits the sale of mutual funds, variable annuities, variable life insurance, unit investment trusts and municipal fund securities (FINRA, Series 6 exam, checked 12 September 2026). Name both if you hold both; if only the first, say so.
A growing occupation, mostly inside agencies
Insurance sales agents held 572,600 jobs in 2025, with projected growth of 3 percent through 2035, a gain of 18,800 positions and about 43,100 openings a year, against a typical entry requirement of a high school diploma or equivalent (BLS Occupational Outlook Handbook, 2025-35 projections).
Where those jobs sit matters. Insurance agencies and brokerages account for 63 percent of employment, self-employed agents for 12 percent, direct insurance carriers other than life, health and medical for 8 percent, and direct health and medical insurance carriers for 5 percent (BLS, May 2025).
Nearly two-thirds of the occupation therefore works for an intermediary rather than a carrier, which is why appointments and lines of authority carry so much weight. An agency hires for what you can place through their existing carrier relationships and what you would add.
Build a snapshot of your key insurance agent skills
Twelve to fourteen entries in four groups, weighted toward coverage work rather than personality.
Coverage and product: Personal auto and homeowners underwriting appetite, Umbrella and excess liability, Small commercial package and workers compensation, Term and permanent life, Medicare supplement, Variable annuity suitability
Book management: Annual household coverage review, Cross-sell and account rounding, Renewal and remarket cycle, Lapse prevention, Premium finance and payment plans
Compliance: Producer licensing and renewal, Continuing education tracking, Carrier appointment records, Suitability documentation, Non-public personal information handling
Systems: Applied Epic, EZLynx, carrier rating portals, comparative raters, e-signature and document management
Name the agency management system and the raters. An agent already working in the system the agency runs is quoting on day three rather than week three.
List your education and certifications
Licenses first, then designations, then the degree. The license outranks the diploma here, and federal data agrees: typical entry-level education for insurance sales agents is a high school diploma or equivalent (BLS Occupational Outlook Handbook, May 2025).
Wisconsin resident producer license #WI-3308291: property, casualty, personal lines, life, and accident and health. National Producer Number 19447206. Non-resident: Illinois #IL-7742168, Minnesota #MN-2290544.
Continuing education: 24 credit hours each biennial cycle including 3 ethics hours, last completed March 2026.
Securities Industry Essentials, FINRA, passed 2022. Series 6, FINRA, registered through the agency's broker-dealer, 2023.
Bachelor of Science, Business Administration, University of Wisconsin-Milwaukee, Milwaukee, WI, 2016
Carrier training: personal lines underwriting schools with four appointed carriers, 2020 to 2025. Commercial package rating workshops, 2024.
List a designation only when you hold it, with the awarding body and the year. Principals know which designations are examinations and which are attendance, and an inflated credential line is the fastest way to lose an otherwise strong file.
Choose the right layout and design
Single column, 10 or 11 point, real table markup for the licensing and book blocks, no photograph. License numbers are text; put nothing that matters inside a graphic.
Name the issuing state, the license number and every line of authority. Give your National Producer Number. Separate resident from non-resident licenses. State the continuing education cycle. List appointments by product type and count them. Say whether you have worked captive, independent or brokerage. Give the book in policies, households and annualised premium, then retention and lapse. Report lines per household with a before and after.
Do not write "licensed and appointed" without saying in what and with whom. Do not imply a line of authority you are only studying for. Do not name an individual policyholder, household or commercial client. Do not present a carrier's book figures as your own production. Do not claim securities registration you do not hold. Do not omit the lapse rate; a retention figure without it invites the question anyway.
Insurance agent job market and outlook
Insurance agents are counted in the Bureau of Labor Statistics occupation for insurance sales agents, one of the few sales occupations still projected to grow.
| Measure | Value |
|---|---|
| Insurance sales agent jobs, 2025 | 572,600 |
| Projected change, 2025-35 | 3% (about as fast as average), +18,800 |
| Projected annual openings | About 43,100 |
| Median annual wage, May 2025 | $62,280 |
| Median hourly wage, May 2025 | $29.94 |
| Typical entry-level education | High school diploma or equivalent |
Source: U.S. Bureau of Labor Statistics, Occupational Outlook Handbook, 2025-35 projections and May 2025 wage data.
Growth of 3 percent with about 43,100 openings a year means most hiring is replacement, but the occupation is not shrinking, which separates it from neighboring sales occupations. The barrier here is regulatory rather than economic: what limits who fills these seats is which licenses, lines and appointments a person holds on the day they apply.
What salary you can expect as an insurance agent
The median annual wage for insurance sales agents was $62,280 as of May 2025, or $29.94 an hour. The lowest 10 percent earned less than $37,330 and the highest 10 percent more than $138,140 (BLS, May 2025).
That spread is unusually wide for an occupation with a high school entry requirement, and it is commission structure rather than base pay. An agent building a book earns near the bottom of the range for two or three years while renewals accumulate, then moves up as the in-force book produces a trail without new production behind it.
Where you work moves the figure. May 2025 medians were $73,440 in direct health and medical insurance carriers, $63,810 in direct insurance carriers other than life, health and medical, and $61,550 in insurance agencies and brokerages (BLS, May 2025). Agencies sit at the lower median while employing 63 percent of the occupation, and the reason is structural: agency producers own more of their upside through commission and renewal trail.
Describe your own compensation model plainly. New and renewal commission on written premium, salary plus commission, or a draw against commission are three different risk positions, and a principal reads a candidate who states theirs as someone who understands what they are being offered.
Key takeaways for an insurance agent resume
- Lead with the issuing state, the license number and every line of authority.
- Give your National Producer Number so every claim is verifiable in one lookup.
- Separate resident from non-resident licenses and name the states.
- List appointments by product type; a license without them places no business.
- State the continuing education cycle and that you finish it early.
- Give the book as policies, households and annualised premium, then retention and lapse.
- Report lines per household with a before and after; that is growth an agency can copy.
Build your insurance agent resume in 15 minutes.
Related sales resume examples
- Travel agent resume
- Sales resume
- Account executive resume
- Sales representative resume
- Car sales resume
- Sales manager resume
- Customer success manager resume
- Account manager resume
- Field sales professional resume
- Sales associate resume
- Telemarketer resume
- Sales engineer resume
Pair it with a matching insurance agent cover letter.
Insurance agent resume questions, answered
How long should an insurance agent resume be?
One page while your book is young, two once you have carried one through several renewal seasons. The second page is the licensing and book detail and the earlier roles.
What do I put on an insurance agent resume with no book yet?
The license first, in full: issuing state, number, lines of authority and your National Producer Number. Then whatever production you have, with real figures rather than percentages of a target. Then any service experience inside an agency, because policies serviced, endorsements processed and first notices of loss taken are all relevant work.
Do I need to list carrier appointments?
Yes, by product type and with a count. A license is permission from the state; an appointment is a carrier authorizing you to represent it, and an agency is assessing how quickly you can place business through relationships they already hold. Do not list a terminated appointment; the carrier filed a notice of it.
Should I put the SIE or a Series registration on an insurance resume?
Only if you hold it, and say which. The Securities Industry Essentials examination is open to anyone aged 18 or older and does not require firm association, with results valid four years, while the Series 6 requires sponsorship by a FINRA member firm and permits the sale of mutual funds, variable annuities, variable life insurance, unit investment trusts and municipal fund securities (FINRA, Securities Industry Essentials and Series 6 exam pages, checked 12 September 2026).
How should I describe commission on a resume?
State the model, not the earnings. New and renewal commission on written premium, salary plus commission, or a draw against commission are three different arrangements, and naming yours tells a principal how you have been paid to think. Then let the book carry the performance argument: policies in force, annualised premium, retention and lines per household beat any income figure.