Rosalind Tamayo Mortgage Loan Processor Tempe, 85281, United States [email protected] · (480) 555-0202
11 September 2026
Ms. Denise Bracewell Processing Manager Cascade Ridge Lending Phoenix, United States
Application for Mortgage Loan Processor, Cascade Ridge Lending
Dear Ms. Bracewell,
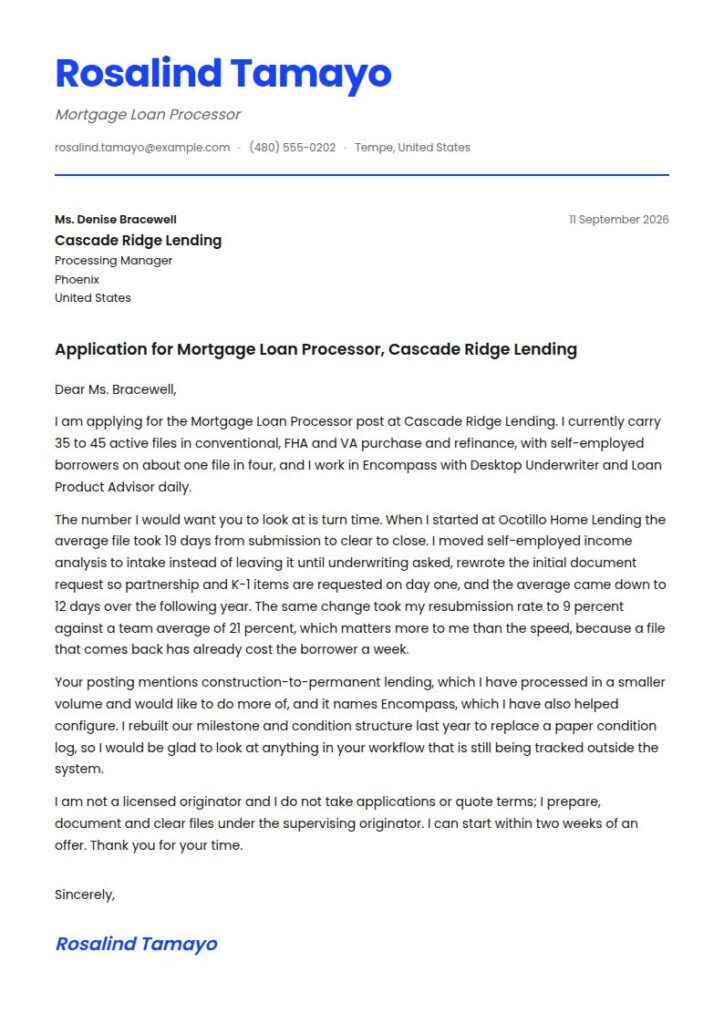
I am applying for the Mortgage Loan Processor post at Cascade Ridge Lending. I currently carry 35 to 45 active files in conventional, FHA and VA purchase and refinance, with self-employed borrowers on about one file in four, and I work in Encompass with Desktop Underwriter and Loan Product Advisor daily.
The number I would want you to look at is turn time. When I started at Ocotillo Home Lending the average file took 19 days from submission to clear to close. I moved self-employed income analysis to intake instead of leaving it until underwriting asked, rewrote the initial document request so partnership and K-1 items are requested on day one, and the average came down to 12 days over the following year. The same change took my resubmission rate to 9 percent against a team average of 21 percent, which matters more to me than the speed, because a file that comes back has already cost the borrower a week.
Your posting mentions construction-to-permanent lending, which I have processed in a smaller volume and would like to do more of, and it names Encompass, which I have also helped configure. I rebuilt our milestone and condition structure last year to replace a paper condition log, so I would be glad to look at anything in your workflow that is still being tracked outside the system.
I am not a licensed originator and I do not take applications or quote terms; I prepare, document and clear files under the supervising originator. I can start within two weeks of an offer. Thank you for your time.
Sincerely, Rosalind Tamayo
Summary
A loan processor cover letter tells a processing manager how many files you can hold, what products they are, how long they take from submission to clearance, and how often underwriting returns them. This guide gives you a full adaptable letter, the openings that work, and the scope language that keeps a processor on the right side of the origination line.
Loan Processor cover letter examples by experience level
A loan processor cover letter is a one page letter that answers a staffing question. A processing manager has a monthly unit count, a target file load per processor, and an empty seat. Your letter says how many files you can hold, in which products, how fast they clear, and how often underwriting sends them back.
That is a narrower letter than most people write, and it is why it works. Nearly every other processor letter in the folder says the same three things about accuracy, organization and communication.
Guide to a loan processor cover letter
This guide and the corresponding loan processor cover letter example will cover:
- How to structure the letter, paragraph by paragraph
- Why pipeline size belongs in the first two sentences
- What a turn time claim looks like when it is written properly
- The scope language that keeps you on the right side of the origination line
- How to write the letter when you are coming from outside mortgage
How to write a loan processor cover letter
| Paragraph | Its job | Length |
|---|---|---|
| Opening | The post, your pipeline size, your product set | 2 to 3 sentences |
| Evidence | One turn time or accuracy number, with the change that produced it | 4 to 5 sentences |
| Fit | Their product mix or system, and what you would take on | 3 to 4 sentences |
| Close | Systems, availability, thank you | 2 sentences |
Lead with capacity, then with accuracy
Capacity gets you read and accuracy gets you hired, in that order. A manager scanning letters first sorts for people who can hold the load, then sorts that group for people underwriting will not have to chase.
So the first sentence is a number of files and a product set: "35 to 45 active files in conventional, FHA and VA purchase and refinance." The second is the accuracy number, with the team or branch comparison that makes it legible. If your employer does not publish a resubmission rate, use closings a month or average days from submission to clear to close, and name the measure.
A loan processor cover letter example you can adapt
Dear Ms. Bracewell,
I am applying for the Mortgage Loan Processor post at Cascade Ridge Lending. I currently carry 35 to 45 active files in conventional, FHA and VA purchase and refinance, with self-employed borrowers on about one file in four, and I work in Encompass with Desktop Underwriter and Loan Product Advisor daily.
The number I would want you to look at is turn time. When I started at Ocotillo Home Lending the average file took 19 days from submission to clear to close. I moved self-employed income analysis to intake instead of leaving it until underwriting asked, rewrote the initial document request so partnership and K-1 items are requested on day one, and the average came down to 12 days over the following year. The same change took my resubmission rate to 9 percent against a team average of 21 percent, which matters more to me than the speed, because a file that comes back has already cost the borrower a week.
Your posting mentions construction-to-permanent lending, which I have processed in a smaller volume and would like to do more of, and it names Encompass, which I have also helped configure. I rebuilt our milestone and condition structure last year to replace a paper condition log, so I would be glad to look at anything in your workflow that is still being tracked outside the system.
I am not a licensed originator and I do not take applications or quote terms; I prepare, document and clear files under the supervising originator. I can start within two weeks of an offer. Thank you for your time.
Sincerely, Rosalind Tamayo
Openings that work
| Instead of | Use |
|---|---|
| I am a detail-oriented professional with a passion for mortgage lending | I carry 35 to 45 active files in conventional, FHA and VA purchase and refinance |
| I am writing to express my interest in your loan processor opening | I am applying for the Mortgage Loan Processor post, and I work in Encompass daily |
| I have a proven track record of closing loans on time | Average submission to clear to close fell from 19 days to 12 over a year |
| I work well under pressure in a fast-paced environment | My resubmission rate is 9 percent against a team average of 21 percent |
The scope sentence, and why it belongs in the letter
A processor prepares and documents the file. An originator takes the application and offers or negotiates terms. Under the SAFE Act rules, an individual who performs "only clerical or support duties" under the supervision of a licensed originator is excluded from loan originator status, as is an individual performing "only purely administrative or clerical tasks on behalf of a loan originator" (12 CFR 1008.103(e)(3)(i) and (e)(4)).
One sentence naming that boundary tells a compliance-aware manager that you understand the line you work inside, and it stops your own claims from reading as licensed activity. If you hold a registration under 12 CFR 1007.103 or a state license, say that instead and give the unique identifier.
Open with the pipeline number and the product set. Give one turn time with a named start and end point. Name the loan origination system and the automated underwriting engines. Say which agency guideline sets you work to. Name one real thing from their posting, such as a product or a system. Keep the scope sentence in, whichever side of it you are on.
Do not write that you originated, structured or quoted loans unless you are registered or licensed, because that is licensed activity. Do not put a borrower name, loan number, address or credit score into the letter, ever. Do not claim the loan officer's production volume as your own. Do not describe yourself as detail-oriented without a number behind it. Do not send a letter with no lender name in it.
Writing the letter from outside mortgage
Plenty of good processors arrive from title, escrow, insurance, collections or medical billing. The letter has to do the translation, because the reader will not do it for you.
| What you did | How it reads to a processing manager |
|---|---|
| Title or escrow file handling | Commitment review, curative work, payoff and lien clearance, closing coordination |
| Insurance claims processing | Documentation against a rule set, volume per adjuster, cycle time to close |
| Collections or accounts receivable | Chasing a missing item to completion, aged item management, contact discipline |
| Medical billing | Coding accuracy, denial and resubmission rates, payer rule sets |
Give the volume you carried and the accuracy you were measured on, then name the mortgage training you have completed. A manager will hire a strong file worker from the wrong industry, but only if the letter builds the bridge.
The clerical half of this work is what automation reaches first
The Bureau of Labor Statistics publishes no Occupational Outlook Handbook profile for loan processor. The closest published occupation, loan interviewers and clerks, had 169,100 jobs and a median annual wage of $50,020 in May 2025, inside a financial clerks group of 1,144,900 jobs with a median of $49,990 (BLS Occupational Outlook Handbook, May 2025).
That group is projected to decline 4 percent between 2025 and 2035, a loss of 45,400 jobs, while still producing about 88,000 openings a year. BLS names the driver directly: "Productivity-enhancing technology is expected to limit demand for other clerks, such as payroll and timekeeping clerks, loan interviewers and clerks, brokerage clerks, and insurance claims and policy processing clerks" (BLS, 2025 to 2035 projections).
Write the letter accordingly. Document collection and data entry are the parts the software takes. Income calculation on a complex borrower, a title exception and a changed circumstance that has to be documented before redisclosure are the parts that still need you, so those are the parts the evidence paragraph should be about.
Length, format and sending it
One page, four paragraphs, 250 to 400 words. PDF unless the lender's portal says otherwise, named for yourself and the post: rosalind-tamayo-loan-processor-cover-letter.pdf.
Use the same numbers as your resume so the two agree. Our loan processor resume example is written with the figures used here.
Key takeaways
- Put the pipeline number and the product set in the first two sentences.
- Give one turn time with a named start and end point, over a stated period.
- Add the accuracy number: resubmission rate, returns, or clean-file percentage.
- Name the loan origination system and the automated underwriting engines.
- Keep the scope sentence in, so nothing reads as unlicensed origination.
- Name one real thing from their posting, such as a product or a system.
- Leave every borrower detail out, and address a named person.
Write your loan processor cover letter in 10 minutes with our AI cover letter builder.
Loan processor cover letter questions, answered
How long should a loan processor cover letter be?
One page, four paragraphs, 250 to 400 words. Processing managers read these between pipeline meetings, and a long letter signals that you do not know which number matters.
What if I do not know my resubmission rate?
Use a measure your employer does publish and say what it is: closings a month, conditions cleared in a typical week, or the count of files returned in a quarter. Naming the measure and the period is what makes it credible, not the size of the number.
Should I mention that I am not licensed?
One sentence, yes. It tells a compliance-aware manager that you know the boundary set out at 12 CFR 1008.103, and it keeps your own description of the work clean. If you are registered under 12 CFR 1007.103 or hold a state license, say that instead and give the unique identifier.
Can I name the lenders and investors I have worked with?
Name your own employers and the agency guideline sets you work to, such as Fannie Mae, Freddie Mac, FHA and VA. Never name a borrower, a loan number or a specific file.
How do I write this letter for a remote processing job?
Add one paragraph on how you hold a pipeline without a desk next to underwriting: the system you work in, how you track conditions, and your response window to a loan officer. Remote processing roles fail on communication latency rather than on file skill, so answer that concern before it is raised.